Why the Lowest Mortgage Rate Often Costs Move-Up Buyers the Most
On a $500,000 mortgage, shaving 0.10% off the rate saves about $500 a year in interest, roughly $42 a month. People moving up to a bigger home in Abbotsford will spend weeks chasing that number, and it is seldom the one that decides what their move costs.
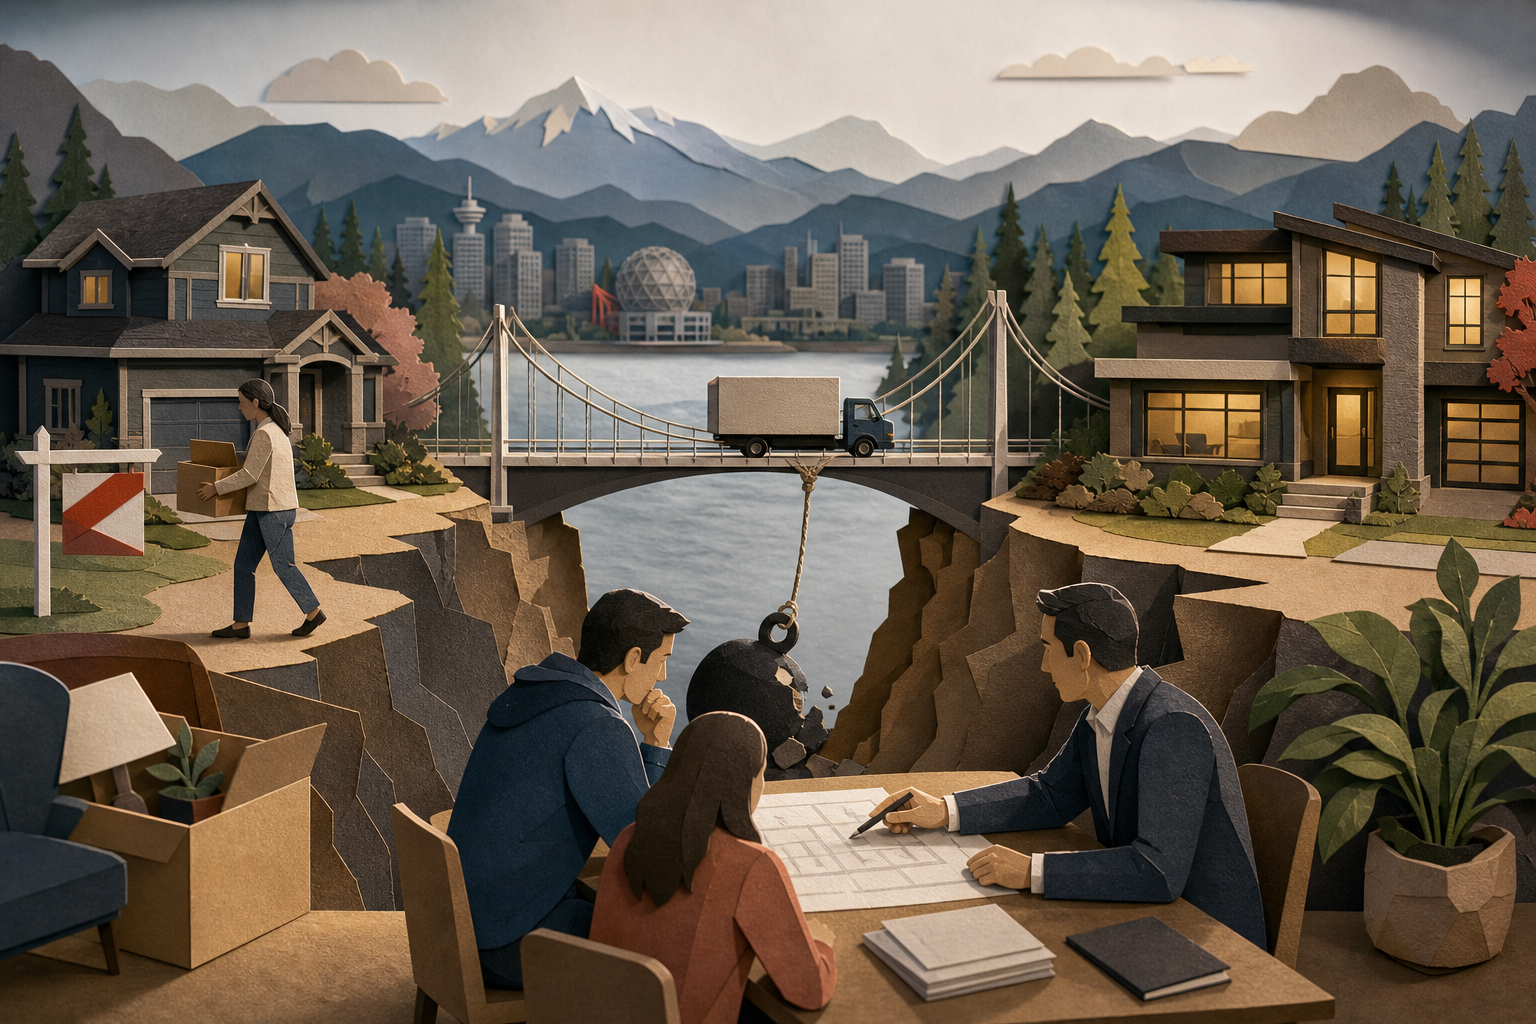
If you're selling one home and buying another, you're juggling two closing dates, a mortgage you already have and a new one you need. The money that matters sits in how your mortgage behaves when plans change: what it costs to break, whether it can follow you to the next house, and how you get from one closing to the other. A rate quote shows you none of that, and those three details can be worth more than every rate discount you'll ever negotiate.
When the lowest rate is the right choice
The usual advice is to compare quotes and take the cheapest, and for plenty of borrowers that's sound. If you'll hold the mortgage for the full term, never refinance and never need extra money from it, the lowest rate is a fair way to choose.
Move-up buyers break those conditions more than anyone. They sell before the term ends, add a renovation, or move again sooner than expected. Many of the lowest advertised rates come from restricted products that limit prepayments, forbid porting, or carry a bona fide sale clause that stops you refinancing or switching lenders unless you sell to an arm's-length buyer. The discount is real. You pay for it with exactly the flexibility your situation depends on.
Why a $42 monthly saving can become a five-figure penalty
Break a variable mortgage early and the penalty is usually three months' interest. Break a fixed one and you typically pay the greater of three months' interest or the interest rate differential (IRD). Many big banks calculate the IRD using their posted rates, which sit well above the discounted rate you actually pay, and that inflates the gap.
Here's an illustrative example. Say the lender's method produces a 1.5% differential on a $480,000 balance with three years left. That's $480,000 × 1.5% × 3, or $21,600. Five years of saving $42 a month comes to about $2,500.
Portability can flip that math. If your current rate is lower than what's on offer in 2026, carrying it to the new home, or blending it with a new rate for the extra money you need, can beat any fresh discount. It only works if the contract allows it and the lender doesn't make it painful.
Then there's the gap between closings. Bridge financing in BC usually needs a firm sale on your current home and a firm purchase on the new one, and it's priced well above prime plus fees. In a Fraser Valley market full of subject-to-sale offers and quick closings, a lender who handles that window poorly costs you more than a slightly higher rate ever would.
Three questions to ask before you compare a single rate
How is the penalty calculated? Ask whether the IRD uses posted or discounted rates, and get it in writing.
Can I port this mortgage or blend and extend it? Ask how many days you'd have between sale and purchase to keep your rate.
Who handles the bridge and both closings? You want one person coordinating the firm dates, the bridge and the funds, so nothing falls through between Friday and Monday.
If a sale will free up cash, add a fourth: how much can you prepay each year without penalty?
Ask those first, then compare rates among the mortgages that pass. A cheap rate on a mortgage that can't move with you will cost you more than a slightly higher one that can.

On a $500,000 mortgage, shaving 0.10% off the rate saves about $500 a year in interest, roughly $42 a month. People moving up to a bigger home in Abbotsford will spend weeks chasing that number, and it is seldom the one that decides what their move costs.
If you're selling one home and buying another, you're juggling two closing dates, a mortgage you already have and a new one you need. The money that matters sits in how your mortgage behaves when plans change: what it costs to break, whether it can follow you to the next house, and how you get from one closing to the other. A rate quote shows you none of that, and those three details can be worth more than every rate discount you'll ever negotiate.
When the lowest rate is the right choice
The usual advice is to compare quotes and take the cheapest, and for plenty of borrowers that's sound. If you'll hold the mortgage for the full term, never refinance and never need extra money from it, the lowest rate is a fair way to choose.
Move-up buyers break those conditions more than anyone. They sell before the term ends, add a renovation, or move again sooner than expected. Many of the lowest advertised rates come from restricted products that limit prepayments, forbid porting, or carry a bona fide sale clause that stops you refinancing or switching lenders unless you sell to an arm's-length buyer. The discount is real. You pay for it with exactly the flexibility your situation depends on.
Why a $42 monthly saving can become a five-figure penalty
Break a variable mortgage early and the penalty is usually three months' interest. Break a fixed one and you typically pay the greater of three months' interest or the interest rate differential (IRD). Many big banks calculate the IRD using their posted rates, which sit well above the discounted rate you actually pay, and that inflates the gap.
Here's an illustrative example. Say the lender's method produces a 1.5% differential on a $480,000 balance with three years left. That's $480,000 × 1.5% × 3, or $21,600. Five years of saving $42 a month comes to about $2,500.
Portability can flip that math. If your current rate is lower than what's on offer in 2026, carrying it to the new home, or blending it with a new rate for the extra money you need, can beat any fresh discount. It only works if the contract allows it and the lender doesn't make it painful.
Then there's the gap between closings. Bridge financing in BC usually needs a firm sale on your current home and a firm purchase on the new one, and it's priced well above prime plus fees. In a Fraser Valley market full of subject-to-sale offers and quick closings, a lender who handles that window poorly costs you more than a slightly higher rate ever would.
Three questions to ask before you compare a single rate
If a sale will free up cash, add a fourth: how much can you prepay each year without penalty?
Ask those first, then compare rates among the mortgages that pass. A cheap rate on a mortgage that can't move with you will cost you more than a slightly higher one that can.
Read Next
The Bank of Canada Didn't Raise Your Fixed Rate. Bond Traders Did.
Canada's 500,000-Homes-a-Year Goal Depends on Fixing the Apprenticeship Pipeline
Stable Home Prices in 2027 Depend on Business Investment Outpacing Slower Population Growth
Markets Expect an October 28 Rate Cut. Your Mortgage Plan Shouldn't.